Yacht Fleet Management Costs: What 15 Vessels Really Run
Quick Summary
- ✓Fifteen vessels is not fifteen times one vessel. The owner-side operating cost does scale almost linearly with hull count, but the management company's own cost base scales on flag diversity, size spread and system variety — not on how many hulls are on the board.
- ✓The ISM Code splits the certification burden the same way. The Safety Management Certificate belongs to the vessel; the Document of Compliance belongs to the company. One DOC covers many hulls, and every SMC issued under it depends on it staying valid.
- ✓Published management fee ranges cluster between 5 and 15 per cent, but no trade body publishes a rate card. The number that matters is what the percentage is charged on — the same fleet can generate roughly $1.3M or $2.6M in fee revenue depending on the basis.
- ✓EU ETS and FuelEU Maritime apply from 5,000 GT. The 40m-plus order book averages around 551 GT. For almost every managed fleet, the regulation absorbing the most worry is the one that does not apply.
- ✓A shoreside team sized for the fleet's average workload is understaffed for four months of the year, because refit slots, Mediterranean season crossovers and audit anniversaries all cluster.
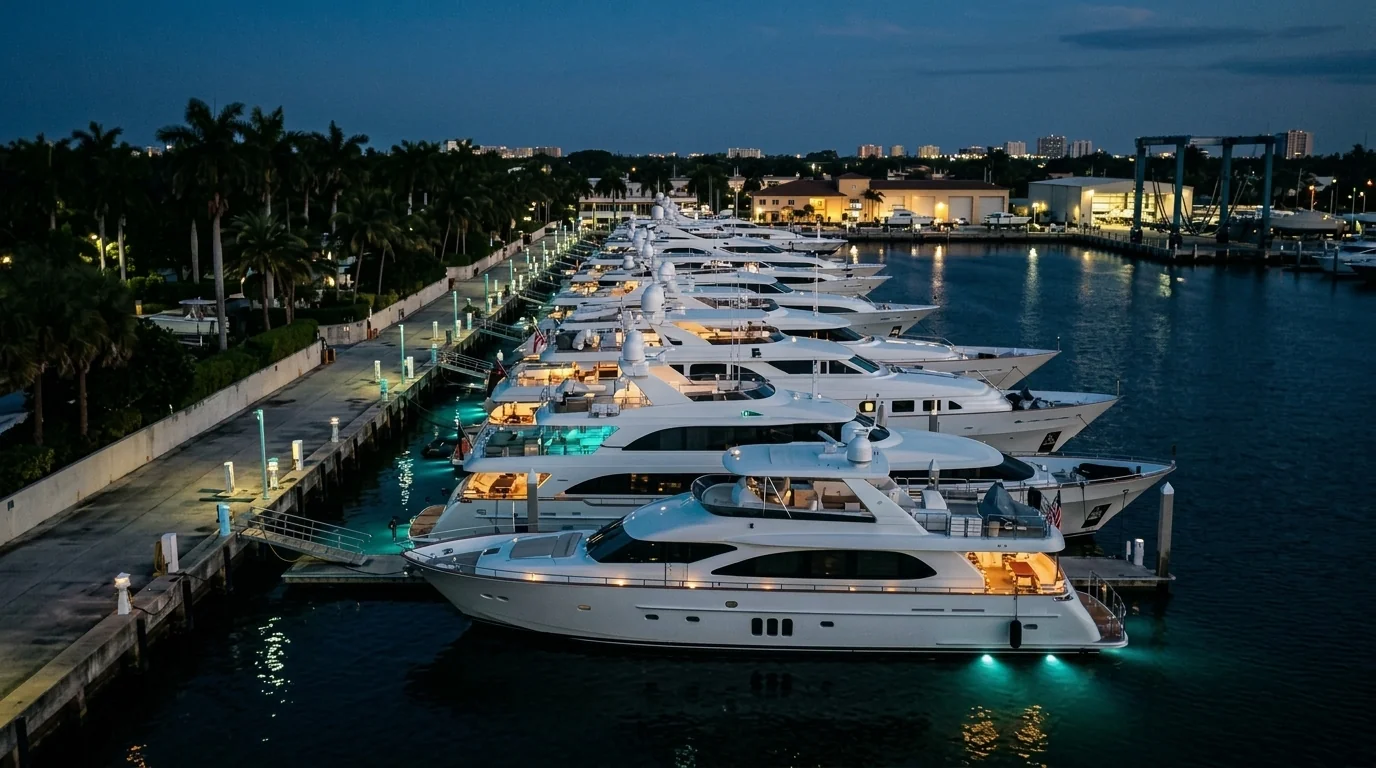
Every October the water between the 17th Street bridge and Lauderdale Marine Center gets crowded in a way that briefly makes the arithmetic of fleet management visible. The 2025 Fort Lauderdale International Boat Show put more than 1,300 vessels across seven venues in front of 100,000-plus visitors and generated a stated $1.78 billion in regional economic impact. A few minutes inland, in an office park, a yacht management company is running its budget cycle, and the wall in the operations room carries a board the show never puts on display: fifteen vessel names, fifteen flags, fifteen sets of audit anniversaries, refit windows and crew rotations.
That board is the actual product. The question the director in front of it is trying to answer sounds simple: what does it cost to run fifteen of these, and how much of that is the owners' money passing through rather than the company's own money going out?
Most cost analysis in this industry stops at one hull. Some lines multiply almost exactly by fifteen. Some barely move. And one category, the one that quietly decides whether a management book is profitable, does not track hull count at all.
The Baseline a Fleet Model Has to Start From
The single-vessel numbers are settled enough to build on. A 30-metre motor yacht worth around $10 million runs close to $1.1 million a year in cash operating cost before depreciation, with crew the largest line at roughly $400,000. A 50-metre vessel does not cost twice that: crew alone roughly triples and the cash figure moves past $3.6 million. The full single-vessel annual operating budget sets out every line, and the crew cost breakdown by role and vessel size does the same for the largest of them.
Those figures are the input here, not the subject. What follows is what happens to them when fifteen vessels sit under one Document of Compliance, one accounting function and one director's signature.
One piece of context sharpens the model. According to the Monaco Yacht Show Market Report 2025, there were 6,174 superyachts over 30 metres in operation as of early August 2025, with 63 per cent of that fleet in the 30-40m band. A realistic 15-vessel book is therefore weighted toward the smaller end, with a few larger hulls carrying outsized weight in both revenue and workload. Any model built on fifteen identical 50-metre vessels is modelling a fleet that does not exist.
What Actually Scales With Hull Count, and What Does Not
The most useful thing a fleet director can do to their own P&L is sort every line into one of three behaviours.
| Behaviour | Lines | Why |
|---|---|---|
| Linear in hull count | Crew, fuel, dockage, insurance premium, maintenance and refit, provisioning, class and flag fees | Each is purchased per vessel. Fifteen hulls need fifteen crews and fifteen berths. Scale changes the price per unit slightly, never the quantity. |
| Sub-linear (real economies of scale) | The Safety Management System, the DPA function, accounting and owner reporting engine, procurement desk, software platform, professional indemnity cover | Built once, applied many times. The marginal cost of the sixteenth vessel against these is genuinely small. |
| Super-linear (the trap) | Flag relationships, size-band diversity, builder and system variety, audit scheduling, staff cover for peak load | Each additional flag, size band or unfamiliar machinery family adds a relationship, a regime and a body of knowledge that has to be held somewhere. |
Almost everything in the first row is the owners' money, flowing through the company and out again, setting the fee base without touching the company's own cost structure. The second row is where the case for professional management genuinely lives. The third row is where management books quietly stop being profitable, and no standard chart of accounts has a line for it. It is why a diverse fleet of fifteen can cost more to manage than a homogeneous fleet of twenty-five. The variable is not hull count. It is heterogeneity.
One DOC, Fifteen SMCs
The ISM Code encodes this split more clearly than any accounting system does. Read structurally rather than as a compliance chore, it is a free map of the company's own cost base.
The Safety Management Certificate is issued to the vessel. The Document of Compliance is issued to the company. Both carry a maximum validity of five years. The DOC requires annual verification within three months either side of its anniversary; each SMC requires at least one intermediate verification between its second and third anniversary. Full ISM applicability begins at 500 GT for commercial yachts on international voyages, and the Maritime Authority of the Cayman Islands confirms an interim DOC is issued when a company first takes operational control of a vessel at or above that threshold.
The SMC, then, is a per-hull cost: fifteen vessels, fifteen certificates, fifteen audit cycles, fifteen sets of drill records. The DOC is a company cost — one system, audited once a year, that does not get more expensive because a sixteenth vessel joined. It is why a management company can add a hull without adding a compliance department.
It is also where the concentration risk sits. Every SMC issued under a DOC depends on that DOC staying valid, so a failed company-level audit does not affect one vessel; it reaches the entire book at once. Fifteen owners, one audit date. That justifies preparation for the company audit that would be disproportionate for any single hull, and the mechanics are in the ISM compliance guide for superyacht operations.
The Red Ensign Group Yacht Code does something similar. In force since 1 January 2019 and updated in 2024, it consolidated the old Large Yacht Code as Part A, covering commercial yachts of 24 metres and above by load line length, and the Passenger Yacht Code as Part B for vessels carrying more than 12 but not more than 36 passengers. Which part a hull falls under changes its survey regime, so a fleet spread across both is running two in parallel.
One regulation generates far more budget anxiety than exposure. EU ETS was extended to shipping from 1 January 2024 and FuelEU Maritime took effect from 1 January 2025, but both apply from 5,000 GT. The 40m-plus superyachts currently in build average around 551 GT. Only the 100m-plus class comes near it. The ten such vessels delivered in 2025 averaged roughly 5,295 GT. For a conventional managed fleet, carbon compliance is not yet a cost line. Budget for the audit that happens every year, not the levy that does not apply.
Flag Diversity Is the Real Multiplier
A fleet of fifteen vessels flying one flag and a fleet of fifteen vessels spread across Cayman, Malta, Marshall Islands and the Isle of Man are not the same business, and the difference does not appear anywhere on a hull count.
Each flag administration brings its own audit relationship, surveyor availability, circulars that have to flow into the Safety Management System, and calendar. Whether a single DOC is recognised across administrations for a multi-flag yacht manager is genuinely unclear from public flag-state material — the registries surveyed for this article publish no explicit policy, and managers describing their own arrangements refer to DOCs issued by specific administrations for the vessels flagged there. That ambiguity is itself a cost, resolved only by asking each registry directly.
So adding a fourth flag costs more than adding a fourth vessel. Vessel four joins an existing system. Flag four creates a relationship, a document-control obligation, an audit slot in a different calendar, and a body of jurisdictional knowledge that one person now holds and may take with them when they leave.
The same applies to machinery. A superintendent covering five vessels from one yard with the same propulsion package is doing one job repeated. A superintendent covering five vessels from four builders, with four generator sets, three stabiliser systems and two entirely different integrated bridge architectures, is doing four jobs. Both appear on the org chart as "five vessels."
Staffing Ashore for the Peak, Paying for It All Year
There is no published industry benchmark for vessels per technical superintendent, which is worth knowing before accepting any figure quoted as one. The commonly repeated "six to eight ships per superintendent" could not be traced to a primary source at all. Career and recruitment sources describe three to six vessels as a working norm, rising toward ten on simpler fleets, but none represent a trade-body study. Commercial shipmanagement proxies are directional only: Bernhard Schulte Shipmanagement publishes around 650-680 vessels supported by roughly 2,000 onshore staff across all functions: a whole-organisation ratio, not a superintendent one.
What is not ambiguous is the shape of the demand curve. Refit slots cluster. Season crossovers cluster. Flag and class anniversaries cluster, because vessels are often certificated in batches. Owner reporting spikes monthly by definition. A shoreside team sized to the fleet's average workload is comfortably staffed for eight months of the year and materially short for the other four.
Three ways out, each with a price. Hire for the peak and carry idle capacity through the shoulder months. Hire for the average and buy contractors at peak-season rates, when surveyor availability is at its worst. Or hire for the average and absorb the overflow through the existing team — the option that appears in no budget and shows up eighteen months later as senior staff turnover, taking with it exactly the jurisdictional and machinery knowledge that flag and builder diversity created.
Where Scale Genuinely Pays
Four advantages are real, though only some can be quantified honestly.
One system, many hulls. The Safety Management System, maintenance regime, reporting templates and onboarding process are built once. Every additional vessel that adopts the existing system rather than requiring a variant is nearly free at the shoreside level — the strongest argument for resisting hulls unlike the existing book.
A fleet loss record is an asset. Marine insurance moved past the peak of its hardening cycle in 2024, and broker commentary into late 2025 described softening of roughly 4 to 7.5 per cent for fleets with good loss records, against hull and machinery rates of 0.7 to 1.5 per cent of insured value for a well-maintained 40-50m vessel. Those figures are broker material rather than an independent survey, so treat them as directional. The structural point survives the hedge: a clean, documented loss history across fifteen hulls is a negotiating position no single owner has, built out of maintenance records the fleet already has to keep.
Purchasing weight, within limits. Consolidating spend strengthens the position on bunkers, parts and yard slots. No published figures quantify the discount available to a yacht management company specifically, and any vendor offering one should be asked for evidence. The mechanism is sound; the magnitude is undocumented.
Berthing. Multi-berth arrangements are cited as a fleet advantage as often as they disappoint, because escalation clauses, minimum-stay commitments and unbundled service fees can erase a headline volume rate — see marina escalation clauses and the fees behind the slip rate.
Note what is absent: crew. Crew is 30 to 40 per cent of a vessel's operating budget and does not get cheaper with fleet size. Quay Crew reported captain salaries in the 70-79m bracket growing around 7 per cent year on year, with 63 per cent of those captains now on time-for-time rotation — a structure requiring two people per seat. A fleet gains something on crew, just not price: a pool of fifteen vessels can move a rotational engineer between hulls in a way a single owner cannot.
An Illustrative 15-Vessel Fleet Model
What follows is a reference model, not an industry statistic: built outward from the published single-vessel figures above, weighted to the real fleet distribution, every number illustrative. No trade body publishes a yacht-management shoreside cost benchmark, which is precisely why fleet directors end up comparing their margin against anecdote.
Fleet composition and owner-side operating cost
| Segment | Hulls | Approx. annual opex each | Subtotal |
|---|---|---|---|
| 30-35m | 9 | ~$1.1M | ~$9.9M |
| 40-50m | 4 | ~$2.2M | ~$8.8M |
| 55-60m | 2 | ~$3.6M | ~$7.2M |
| Total fleet operating cost | 15 | — | ~$25.9M |
That $25.9 million is the owners' money — the fee base, the reporting burden and the procurement volume at once, and almost none of it the management company's cost.
The management company's own annual cost base
| Function | Illustrative headcount | Notes |
|---|---|---|
| Managing director / DPA | 1 | Company-level ISM accountability sits here |
| Technical superintendents | 3 | ~5 hulls each, mid-range of the working norm |
| Fleet accounting and owner reporting | 2 | Monthly cycle across 15 owners |
| Crew management / employer-of-record | 1 | SEAs, rotations, MLC financial security |
| Compliance and QHSE | 1 | DOC maintenance, audit programme, document control |
| Administration | 1 | — |
| Shoreside total | 9 | Plus office, professional indemnity, travel, systems |
Nine fully loaded shoreside roles, plus premises, professional indemnity cover, travel to vessels and audits across multiple jurisdictions, and systems, puts a 15-vessel management company's own annual cost base in the low seven figures. That is what the management fee has to cover, and it almost never appears in a conversation about whether the fee is 10 per cent or 12.
Ten Per Cent of What?
Published fee ranges cluster between 5 and 15 per cent, drawn largely from management companies' own material; no trade body publishes an audited rate card. Flat retainers are equally common — quoted around €60,000 a year for a 24-metre vessel, rising past €600,000 for 60m-plus hulls. All vendor-published, and to be treated accordingly.
Now apply two defensible readings to the same fifteen vessels.
Reading one — percentage of full operating budget. Ten per cent of $25.9 million is roughly $2.6 million in gross fee revenue. Against a low-seven-figure shoreside cost base, that is a business with a real margin.
Reading two — the published per-vessel management line. The single-vessel budget above carries management and administration at $60,000 on a 30-metre yacht, about 5.5 per cent of that vessel's cash budget. Scale that convention across the same fleet, at roughly $60,000 for nine hulls, $110,000 for four and $160,000 for two, and gross fee revenue lands near $1.3 million.
Same fifteen vessels. Same work. A two-fold difference in revenue, produced entirely by what the percentage is charged on.
That is why margin comparisons between management companies are usually meaningless. "We charge twelve per cent" says nothing about whether a company is better paid than one charging ten. The basis does. A book with an inherited mix (some contracts on full operating budget, some on a narrower administrative scope, some on flat retainers signed years ago and never re-cut) will show variation between vessels that looks like operational performance and is actually contract structure.
The Reporting Tax
Owner reporting is the line that scales worst and gets budgeted least.
No published survey quantifies the hours a yacht management company spends compiling owner reports. The figure OwlMar works from, over 20 hours a month for a fleet director's team, comes from its own persona research rather than industry data, and is a working assumption, not a benchmark. The structure of the problem is not in question. Every owner expects a monthly pack, assembled from the same sources: the maintenance system, the accounting system, the crew records, the fuel and dockage invoices. Those four sources rarely share a database, so an administrator assembles the pack by hand: exporting from the maintenance system, reconciling against the accounting ledger, then re-keying the result into the owner's reporting template.
That work is linear in hull count, not billable separately, and lands on the same days every month for every vessel at once — the peak-load problem above, repeated twelve times a year. It is also the most visible thing the company produces, and inconsistent reporting across a fleet is a retention risk in a business where fees are under constant scrutiny.
What a Fleet Director Should Actually Measure
None of the following appears on a standard P&L, which is why the cost structure described above stays invisible. Six numbers make it visible.
- Shoreside cost per managed vessel per year. Company cost base divided by hull count. The real unit economic, and it should be trended rather than calculated once.
- Hulls per superintendent, weighted. Count flags and system families, not hulls. Five vessels across four builders and three flags is not a five-vessel load.
- DOC relationships held. How many flag administrations the company holds company-level certification with. Each is a fixed annual cost hull count will never reveal.
- Company-level audit days versus vessel-level audit days. Splitting these separates the cost that scales with the fleet from the cost that does not.
- Hours to produce one vessel's monthly owner reporting pack. Measured, not estimated. This decides whether any systems investment pays back.
- Fee basis per contract, in one place. Not the percentage — the basis. A book where this has never been written down is a book where nobody knows which vessels are profitable.
Instrument those six and it becomes possible to tell the difference between a vessel that is genuinely unprofitable and a contract priced on the wrong basis three years ago. The two look identical on a monthly report and have completely different solutions.
What the Software Line Has to Earn
Systems sit squarely in the sub-linear row and should be assessed on that basis rather than on features.
OwlMar's Fleet plan is $999 a month including five vessels, with additional vessels at $199. For the fleet modelled above that is $2,989 a month, or roughly $35,900 a year: about 0.14 per cent of the fleet's ~$25.9 million operating cost, and between 1.4 and 2.8 per cent of gross fee revenue of $1.3 to $2.6 million. The second figure is the honest one, because the licence comes out of the management fee, not the owners' budgets.
At that price the platform has to save roughly one part-time administrative role to break even; anything beyond that is margin. The place to look is the reporting tax and the audit programme — consolidated fleet compliance status, document control that pushes a flag circular to every affected vessel at once, and owner reporting assembled from data already captured rather than re-keyed. The broader case for fleet-level yacht management software covers what that means in practice; the fleet and enterprise tiers differ mainly in where multi-flag and multi-entity requirements start. Measurement five above is what turns this from a sales argument into a decision.
The Bottom Line
The owner-side spend on crew, fuel, dockage, insurance and maintenance scales almost exactly with hull count, because each is bought per hull. That money passes through and sets the fee base. The management company's own cost base scales on something else: the number of flags, the spread of size bands, the variety of machinery, and the peak rather than the average of a workload that clusters into four months of the year. A homogeneous fleet of twenty-five can be cheaper to run than a diverse fleet of fifteen, and no hull count will ever show it.
The ISM Code has been describing this split all along. The SMC belongs to the vessel and multiplies. The DOC belongs to the company and does not. A fleet director who sorts every P&L line into those two categories, and writes down the fee basis on every contract in the book, will see their own business more clearly than most published industry commentary allows, because that commentary is largely written by parties with an interest in the number.
The fee is not the problem. The basis, the heterogeneity and the peak are.
Sources & References
- Monaco Yacht Show Market Report 2025 (SuperYacht Times data) — fleet size, segment distribution, order book. monacoyachtshow.com
- ISM Code, IMO Resolution A.741(18), codified in SOLAS Chapter IX — DOC and SMC issuance, validity, verification intervals.
- Maritime Authority of the Cayman Islands guidance notes — interim DOC on taking operational control of a vessel of 500 GT and above. cishipping.com
- Red Ensign Group Yacht Code (in force 1 January 2019, updated 2024) — Part A and Part B scope. redensigngroup.org
- MLC 2006 and the 2022 amendments (in force 23 December 2024) — seafarer employment agreements, financial security for repatriation.
- European Commission and EMSA — EU ETS extension to shipping (1 January 2024) and FuelEU Maritime (1 January 2025), both from 5,000 GT. climate.ec.europa.eu
- FLIBS 2025 global impact release — economic impact, attendance, exhibitors. flibs.com
- Bernhard Schulte Shipmanagement fleet and onshore staff figures — directional proxy only. bs-shipmanagement.com
- Quay Crew salary benchmarks and broker commentary on hull and machinery rates through Q4 2025, both via secondary citation. Interested-party sources; directional, not independent surveys.
- Management fee ranges and retainers come from management companies' own published material. No trade body publishes an audited rate card.
Fleet composition, shoreside headcount and fee revenue figures here are illustrative models built outward from OwlMar's published single-vessel operating budget, not surveyed statistics.
Written by
OwlMar Team
Maritime Technology Experts
The OwlMar team brings decades of combined experience in maritime operations, marine engineering, and software development. We write from real-world experience managing vessels from 30ft cruisers to 100m+ superyachts.
Ready to Simplify Your Yacht Management?
OwlMar helps owner-operators track maintenance, manage costs, and get AI-powered diagnostic assistance. Start your free trial today.
Request a DemoRelated Articles
Superyacht Operating Costs Per Year: A Full Budget Breakdown
Superyacht operating costs per year run 8-12% of a vessel's value. A line-by-line annual budget for a 30m and a 50m yacht, from crew to depreciation.
IDEA Yacht Alternative: An Honest Fleet Comparison
An honest IDEA Yacht alternative for fleet and superyacht operators: where IDEA's 25-year incumbency genuinely wins, and where OwlMar closes the gap.
Hurricane Prep Yacht Checklist: Owners and Charter Fleets
A hurricane prep yacht checklist for single-vessel owners and charter fleets — insurance warranties, the haul-or-stay call, guest bookings, APA, and crew.